🚨 2026 Update: SSM Is Looking at Sustainability Reporting Under the Companies Act
This is one of the developments Malaysian private companies should pay attention to.
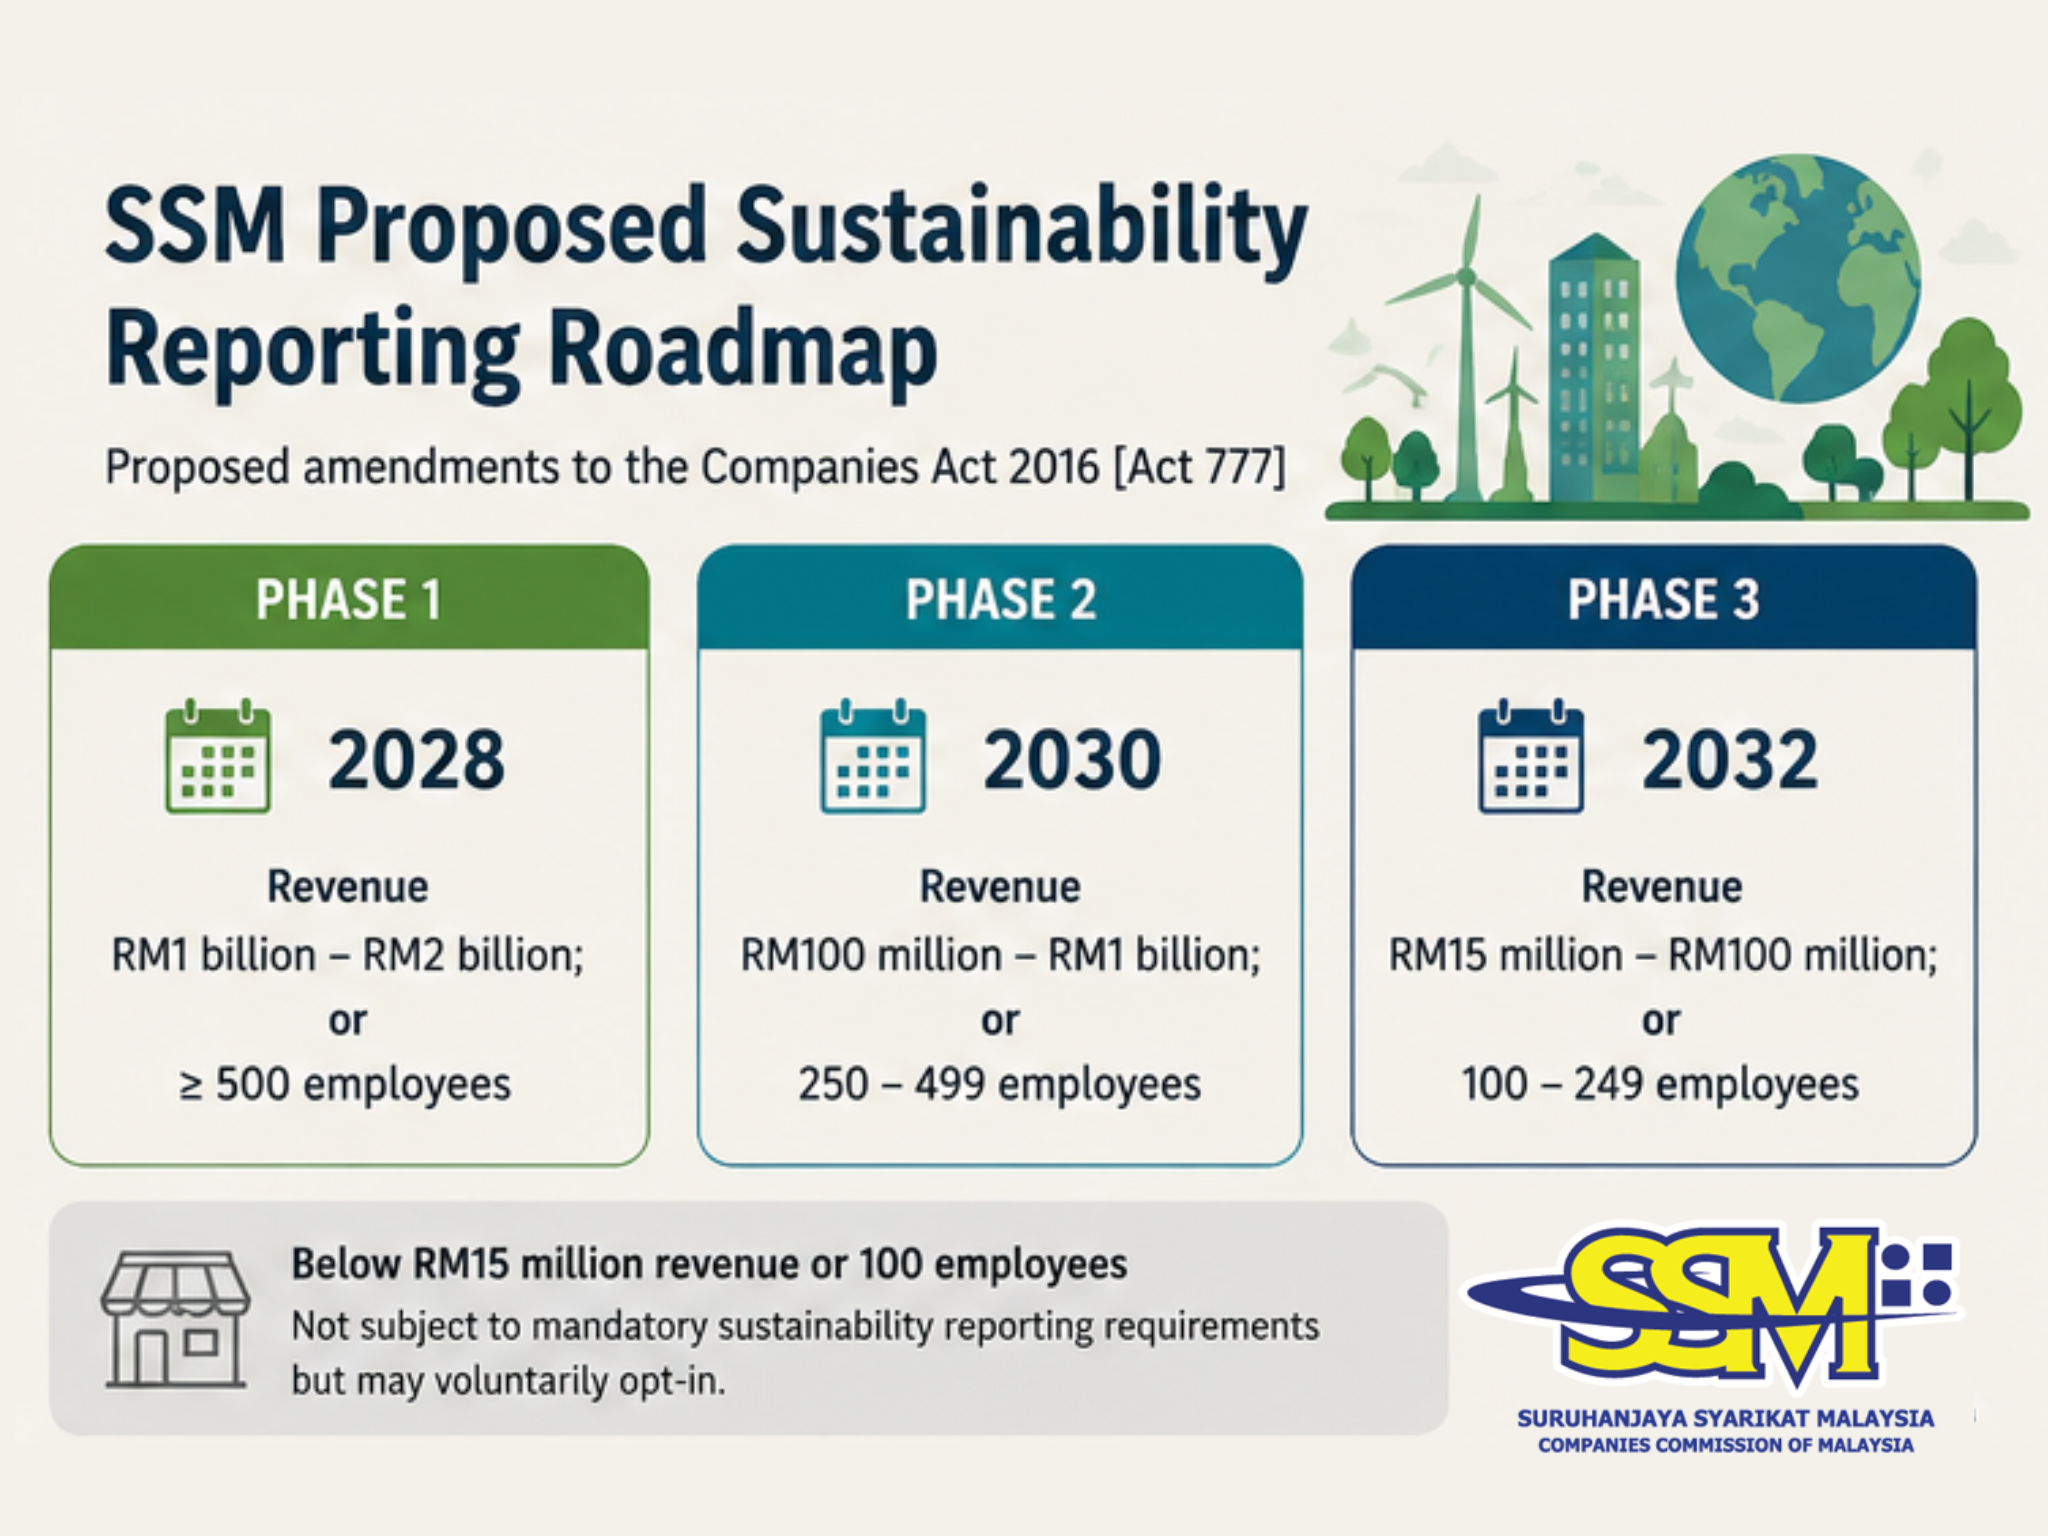
On 30 April 2026, SSM issued a Consultative Document on the Proposed Amendments to the Companies Act 2016 [Act 777] on Sustainability Reporting. A revised Section F was subsequently issued on 22 May 2026, and the consultation deadline was extended to 16 June 2026.
SSM — Proposed Amendments to the Companies Act 2016 on Sustainability Reporting
The important word here is "proposed."
This consultation should not be interpreted as meaning that every Malaysian SME is already legally required to prepare a sustainability report today.
Instead, it indicates that Malaysia is working towards establishing a broader legal foundation for sustainability reporting.
This matters because the reporting landscape may eventually extend beyond the largest listed and non-listed companies currently captured under the NSRF.
Does This Mean SMEs Need to Prepare Sustainability Reports Now?
Not necessarily.
Under the existing NSRF scope, many ordinary Malaysian SMEs are not directly captured by the RM2 billion large non-listed company threshold.
However, that does not mean SMEs should completely ignore sustainability reporting.
There is a difference between:
"Am I legally required to report?"
and
"Will my business increasingly be asked for sustainability information?"
The second question is becoming increasingly relevant.
Why Sustainability Reporting Can Still Affect SMEs
Even where an SME is not directly subject to mandatory sustainability reporting, it may operate within the supply chain of a larger company.
The NSRF itself specifically recognises that non-listed companies form an integral part of broader supply chains.
This can create a knock-on effect.
For example, a larger customer may need information from its suppliers concerning:
Electricity consumption
Fuel consumption
Carbon emissions
Waste management
Environmental policies
Employee practices
Supply-chain standards
Internationally, sustainability information is also increasingly relevant to procurement, access to capital, corporate reputation and business relationships.
Therefore, even if your SME does not need to issue a formal sustainability report today, your customers, investors, lenders or multinational partners may increasingly ask you for sustainability-related data.
Understanding Scope 1, Scope 2 and Scope 3 Emissions
One area businesses are likely to encounter frequently is greenhouse gas or GHG emissions reporting.
Scope 1 — Direct Emissions
These are emissions directly generated by sources owned or controlled by the company.
Examples may include fuel consumed by company vehicles or certain equipment.
Scope 2 — Purchased Energy
These are indirect emissions associated with purchased electricity or other forms of acquired energy used by the business.
Scope 3 — Value Chain Emissions
Scope 3 generally covers other indirect emissions occurring across the company's value chain.
This is particularly relevant to SMEs.
If an SME supplies goods or services to a larger company, information relating to the SME's activities could potentially contribute to that larger company's Scope 3 calculations.
Under Malaysia's NSRF, transitional reliefs have also been provided because Scope 3 data can be significantly more challenging to collect.
Sustainability Reporting Is Becoming More Like Financial Reporting
One major direction of sustainability reporting is towards greater consistency, reliability and comparability.
Traditional ESG reports were sometimes largely narrative:
"We care about the environment."
"We support our employees."
"We are committed to sustainability."
Modern sustainability reporting increasingly expects businesses to support statements with measurable information.
For example:
General Statement | More Structured Reporting |
We reduce electricity usage | Annual electricity consumption |
We care about employees | Turnover, training and safety data |
We reduce carbon emissions | Scope 1, 2 and relevant Scope 3 emissions |
We manage climate risks | Identified risks, financial implications and controls |
We support sustainability | Targets, KPIs and progress |
This is one reason sustainability information is increasingly intersecting with the work of finance, accounting, risk management and internal control teams, rather than being treated purely as a marketing exercise.
PwC similarly describes ESG reporting as requiring companies to gather and report relevant non-financial information and to establish processes for obtaining the required data.
External Assurance Is Also Coming Into the Picture
Another important development is assurance.
The NSRF explains that external assurance is intended to improve the reliability of sustainability disclosures and address concerns around greenwashing.
Its stated aim is reasonable assurance over Scope 1 and Scope 2 GHG emissions, beginning with Group 1 from annual reporting periods starting on or after 1 January 2027, followed by Group 2 in 2028 and Group 3 in 2029. However, the framework notes that the mandatory assurance timeline remains subject to further consultation.
In practical terms, sustainability information is moving towards a world where businesses may increasingly need to document, measure and substantiate what they report.
What Should Malaysian SMEs Start Doing?
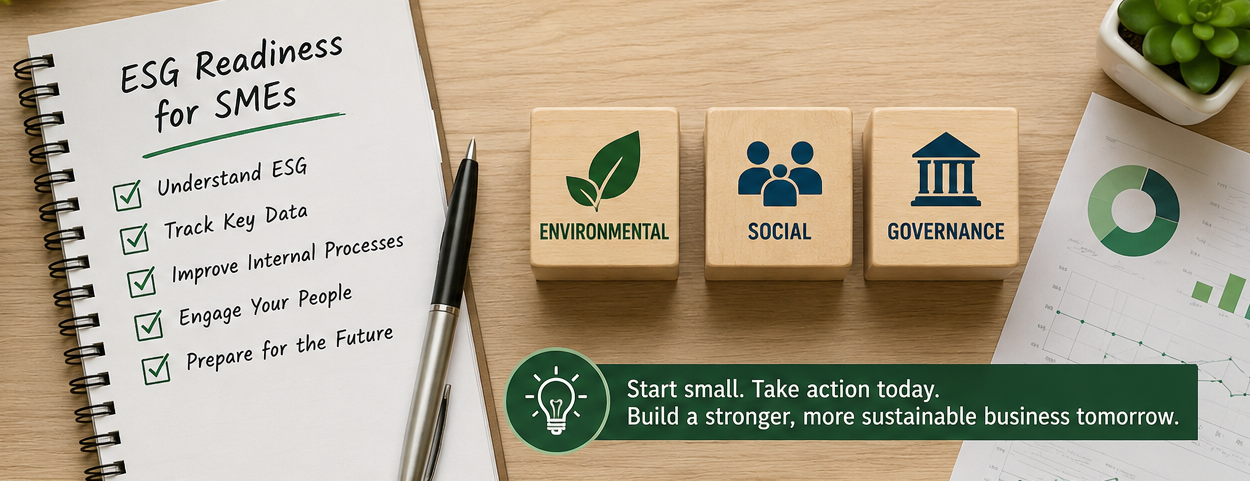
For most SMEs, there is no need to immediately produce a complicated 50-page ESG report.
A better starting point is to build the underlying data and processes.
Businesses can begin by:
Identify the sustainability issues relevant to the business
Consider energy, waste, employees, supply chains, governance and climate-related risks.
Start collecting basic data
Electricity bills, fuel usage, waste records, employee information and other relevant operational data are good starting points.
Determine what customers are asking for
Companies supplying multinational corporations or larger listed companies should pay particular attention to ESG questionnaires and supplier requirements.
Establish responsibilities internally
Sustainability reporting should not belong to one department alone. Finance, HR, operations, procurement and management may all contribute data.
Keep proper supporting records
Just as accounting figures require supporting documents, sustainability information should also be traceable and supportable.
Follow regulatory developments
Businesses should continue monitoring developments involving the NSRF, SSM, Bursa Malaysia and other relevant regulators.
A materiality assessment can also help businesses identify which sustainability issues are most relevant instead of attempting to measure everything at once.
The Direction Is Clear: Sustainability Data Is Becoming Business Data
For many SMEs, sustainability reporting may still feel like something for the future.
But Malaysia's NSRF and the latest 2026 SSM consultation indicate that sustainability disclosure is becoming increasingly integrated into the country's corporate reporting framework.
The NSRF itself provides for amendments across relevant legislation, rules and guidelines, including the Financial Reporting Act 1997, Companies Act 2016, securities legislation and Bursa Malaysia Listing Requirements.
The practical takeaway for business owners is therefore not to panic—but also not to wait until reporting becomes mandatory before organising the necessary information.
Companies that begin building proper records, internal controls and sustainability data today may find it much easier to respond when customers, banks, investors or regulators request this information later.
Need Help Preparing Your Business for Better Reporting?
Sustainability reporting increasingly connects financial reporting, internal controls, data management and business compliance.
HBA Global Consultancy can assist businesses in strengthening their accounting records, management reporting and internal processes so that important business information is better organised and ready for evolving reporting requirements.
📞 Contact Us to learn more about how your business can improve its reporting and compliance readiness.
Disclaimer
This article is provided for general informational purposes only and does not constitute legal, ESG, sustainability, accounting or other professional advice.
Malaysia's sustainability reporting framework continues to evolve. In particular, SSM's 2026 proposed amendments to the Companies Act 2016 discussed above were issued as a consultation proposal and should not be interpreted as final legislation or as imposing the proposed requirements on all Malaysian companies at the date of this article.
Businesses should refer to the latest requirements and announcements issued by the Securities Commission Malaysia, SSM, Bursa Malaysia and other applicable regulators, and seek professional advice where necessary.